RSS

New property listed in Zone 56, Edmonton

I have listed a new property at 108 103 AMBLESIDE Drive SW in Edmonton. See details here

Welcome to this bright & beautifully updated main-floor condo in the heart of Ambleside. Perfect for those who prefer main-floor living without relying on an elevator, this west-facing 2-bed home offers abundant natural light, soft modern colours & new laminate plank flooring. The spacious kitchen features plenty of cabinetry, while the generous balcony provides a wonderful outdoor space to relax or entertain. The primary bedroom includes a closet organizer. Just steps from the stairway & rear entrance, enjoy easy access to the garage & convenient access to Currents of Windermere. Parks, walking trails & public transit are all within walking distance. Enjoy exceptional convenience with Safeway, Superstore, Walmart, restaurants, Tim Hortons & medical services nearby. Anthony Henday is just minutes away. A fantastic opportunity for comfortable, low-maintenance living in one of Southwest Edmonton’s most desirable communities.

Read

Alberta Housing Market Forecast 2026: What It Means for Edmonton

Why Alberta’s Average Home Price Growth Is Forecast to Outpace Canada’s in 2026

The Alberta housing market forecast for 2026 points to stronger average home price growth than the national outlook—but what does this mean for Edmonton home buyers and sellers?

According to the Canadian Real Estate Association’s (CREA) October 16, 2026 forecast, Alberta’s average residential sale price is expected to rise 3.1% in 2026, compared with 0.2% nationally. Ontario and British Columbia are forecast to record declines of 3.0% and 0.8%, respectively.

These are forecasts for annual provincial averages, rather than a prediction for the value of any individual Edmonton home.

Alberta vs. Canada: What the Numbers Show

The wider provincial picture provides useful context. Newfoundland and Labrador leads the 2026 forecast at 5.7%, followed by Saskatchewan at 5.0% and Quebec at 4.0%. Alberta’s projected growth exceeds the national average, although it is not the highest among the provinces.

2026 average home price growth forecast across Canada’s provinces, highlighting Alberta at 3.1% compared with the national forecast of 0.2%. Source: CREA.

Alberta’s average residential sale price is forecast to reach approximately $529,033 in 2026, increasing to $537,857 in 2027, a further 1.7% annual gain.

Nationally, CREA forecasts an average price of $681,681 in 2026 and $689,909 in 2027, with growth of 1.2% in the latter year.

Fewer Home Sales, but Positive Average Price Growth

Price growth and sales activity can move in different directions.

CREA projects approximately 70,045 Alberta home sales in 2026, down 9.0%, followed by 72,936 sales in 2027, an increase of 4.1%. National sales are forecast to fall 5.2% to 444,530 in 2026, then rise 4.4% to 464,235 in 2027.

For sellers, my advice is to focus on comparable properties, presentation and a realistic asking price. A positive provincial forecast should not replace an assessment of the competition your home faces today.

For buyers, I recommend comparing recent sales, reviewing available inventory and deciding what fits comfortably within your budget. Whether there is room to negotiate will depend on the specific property and local market conditions.

What Does This Mean for the Edmonton Real Estate Market?

A provincial average cannot tell you what a particular Edmonton property should sell for.

If you are considering Windermere, Keswick, Terwillegar, Riverbend or Chappelle, I recommend looking closely at the neighbourhood and property type that match your plans. Compare recent sold prices, active listings, condition and time on the market.

A detached home, half duplex, townhome and condominium each need their own comparison. The same approach applies whether you are buying your first home, moving into a larger property or preparing to sell in Southwest Edmonton.

Nooran Ostadeian, Edmonton REALTOR® with RE/MAX Elite, sharing her perspective on Alberta’s 2026 housing market forecast.

My Perspective as an Edmonton REALTOR

Having worked in Edmonton real estate since 2007, I’ve experienced changing market conditions firsthand.

Alberta’s projected price growth is encouraging, but provincial forecasts are only a starting point. Before making a decision, it’s important to understand what’s happening in your neighbourhood and with properties similar to yours.

Your next move should reflect your home, your neighbourhood and your goals.

Whether you’re buying, selling or relocating to Southwest Edmonton, I’m happy to help you compare your options and build a plan based on current local market activity.


Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Source: Canadian Real Estate Association (CREA), Quarterly Housing Market Forecast, October 16, 2026. Provincial forecasts are not Edmonton-specific and may change as economic conditions evolve.

Read

Condo or House in Edmonton? 7 Questions First-Time Buyers Should Answer First

For many Edmonton first-time buyers, the biggest decision is not whether to buy. It is what kind of home to buy. Should you choose a condominium apartment, a townhome, a duplex, or a detached house? Is a lower-maintenance condo the smarter first step? Is a house worth the added maintenance and higher purchase price? And how do condo fees change the real monthly cost?

There is no single right answer. The better choice is the property type that fits your budget, lifestyle, comfort with maintenance, location priorities, and future plans. A condo can be an excellent first home for one buyer and a poor fit for another. The same is true of a detached house.

Rather than starting with a label like “condo” or “house,” start with the questions below. They will help you compare options more clearly and focus on the things that matter after possession day—not just the features that look good in photos.

1. What do you need your home to do for you every day?

Start with your life, not the property type. How do you spend your weekdays? Do you work from home? Do you travel often? Do you have children, pets, hobbies, or a vehicle that needs a garage? Do you want to walk to coffee shops, restaurants, transit, or work? Do you value a private yard, balcony, storage space, or a lock-and-leave lifestyle?

A condominium may suit a buyer who wants less exterior maintenance, a central location, and convenient access to amenities. A detached house may suit a buyer who values private outdoor space, more separation from neighbours, a garage, room to grow, or the freedom to personalize the property. A townhome or duplex can be a middle ground, offering more space than an apartment-style condo while requiring less yard work than some detached homes.

There is no universal hierarchy where a house is always better than a condo. A well-located, well-run condo that supports your life can be a strong purchase. A detached house that overwhelms your budget or takes too much time to maintain can become a source of stress.

Ask yourself:

•Do I want outdoor space, or would I rather spend weekends free from yard work?
•Is a balcony enough, or do I truly need a yard?
•How important are privacy and noise control?
•Will I use shared amenities if I pay for them through condo fees?
•Do I need storage, a workshop, multiple parking stalls, or a garage?
•Does the location reduce my commute or make daily errands easier?

Your answers should drive the search.

2. What is the real monthly cost—not just the list price?

A condo’s purchase price may be lower than that of a detached home in the same area, but you need to look at the complete monthly cost. A condo buyer typically pays a monthly condo fee in addition to the mortgage, property taxes, home insurance, and utilities. Some fees cover heat, water, sewer, snow removal, landscaping, building insurance, exterior maintenance, reserve-fund contributions, or amenities. Others cover fewer items.

A detached house usually has no condo fee, but the owner is responsible for the full cost of repairs and maintenance. The roof, driveway, furnace, siding, yard, fence, sewer line, and exterior upkeep are all your responsibility. You may have a homeowner association fee in some communities, so never assume “house” means no recurring community cost.

The right comparison is not: “This condo is cheaper than that house.”

It is: “What will it cost me each month to own, insure, heat, maintain, and enjoy each option?”

When you compare properties, make a simple ownership-cost worksheet. Include the mortgage payment, property taxes, insurance, estimated utilities, condo fee where applicable, parking, maintenance savings, and a reserve for future repairs. A mortgage professional can help estimate financing costs. Your REALTOR® can help you identify property-specific considerations. You should make the final decision based on the budget that gives you confidence.

A condo fee should not automatically scare you away. It is money paid for a purpose. The key questions are what the fee covers, whether the amount appears sustainable, and whether the condominium corporation is planning responsibly for future costs.

3. How much maintenance are you truly ready to manage?

Homeownership comes with maintenance in every property type. The difference is who manages it and how directly you pay for it.

In a condominium, the corporation is generally responsible for common property, while you are responsible for your unit and your share of the corporation’s obligations. Depending on the complex, the condo corporation may organize exterior repairs, landscaping, snow removal, roofing, building systems, and common spaces. You still need to care for your unit, but you are not independently coordinating every exterior task.

With a detached house, you make the decisions and you take on the responsibility. Some buyers love that control. You can choose when to paint, landscape, replace a fence, improve the yard, or renovate. You are also responsible for budgeting, hiring help, and handling unexpected repairs.

Think honestly about your time, interest, and financial flexibility. A house can be a wonderful choice if you enjoy projects and have room in your budget for maintenance. A condo can be the better choice if you value predictable shared maintenance, travel frequently, or would rather spend your free time elsewhere.

First-time buyers often focus on the interior because that is where they spend time during a showing. Look outside too. If you buy a house, what condition are the roof, grading, eavestroughs, windows, driveway, deck, fencing, and landscaping in? If you buy a condo, what do the building exterior, parkade, hallways, roof, elevators, landscaping, and common areas tell you about ongoing maintenance?

4. How important is your Edmonton location and commute?

Property type and location are closely connected. Depending on your budget, you may be choosing between a smaller condo closer to central Edmonton, work, transit, or established amenities and a larger home farther away. Neither option is automatically better. The value of the location depends on your routine.

Try the commute at the times you would actually travel. Visit the area on a weekday evening and a weekend. Look at nearby grocery stores, parks, schools, transit options, walking paths, recreation facilities, medical services, and access to major roads. Notice traffic, parking, noise, and the feel of the immediate block.

A buyer who spends less time commuting may gain time for family, fitness, social life, or work. A buyer who chooses more space may gain a home office, yard, garage, or room for a growing household. Both can be smart decisions when they are intentional.

Ask yourself: Would I rather have more space, a shorter commute, lower maintenance, a yard, newer finishes, or a specific neighbourhood? You may not be able to maximize all of them at the same price point. Knowing your top two or three priorities helps you choose without regret.

Need help narrowing down your options?

Nooran Ostadeian, REALTOR with RE/MAX Elite Edmonton, can help you compare condos, townhomes, duplexes, and detached homes based on your budget, preferred neighbourhoods, and everyday needs. Book a complimentary consultation


5. How much control do you want over rules and changes?

Condominium living comes with bylaws and rules. These can address pets, rentals, renovations, noise, parking, balcony use, short-term rentals, smoking, move-ins, and use of common areas. Some buyers appreciate the structure because it can help keep the property orderly. Others find it restrictive.

Before buying a condo, do not assume that a rule will be flexible because you personally find it reasonable. Read the bylaws. Ask how pet approvals, renovations, parking, rentals, and other issues are handled. If a certain lifestyle requirement matters to you—such as a large dog, a home business, multiple vehicles, a specific renovation, or a future rental plan—investigate it before conditions are removed.

A detached house generally gives you more day-to-day control, but it still may be subject to municipal bylaws, zoning, easements, utility rights-of-way, development rules, and homeowner association obligations. Freedom is not the same as no rules. It simply looks different.

The question is not whether rules are good or bad. The question is whether the property’s rules are compatible with how you want to live.

6. Have you looked beyond the condo fee to the condo documents?

This is one of the most important questions for condominium buyers. Condo fees are only the beginning. A well-informed buyer reviews the condominium corporation’s financial position, reserve fund, insurance, meeting minutes, bylaws, budget, planned work, and other documents that may reveal future expenses or restrictions.

Alberta condominium corporations are required to establish and maintain a capital replacement reserve fund for major repairs and replacements of property and common property. That does not mean every building will have identical financial strength or the same upcoming repair needs. Age, design, maintenance history, recent work, and future plans can all matter.

The Government of Alberta notes that condominium buyers may choose to have technical documents reviewed, including the condominium plan, bylaws, management agreement, phased-development disclosure, and home warranty contract. Alberta also requires condominium corporations to keep specified documents available to owners, purchasers, and mortgagees upon request. Many buyers hire a qualified condo-document reviewer and may also seek legal advice.

When you review condo documents, look for answers to questions such as:

•What does the condo fee cover today?
•Has the fee increased recently, and why?
•Is the reserve fund consistent with the building’s expected future repairs?
•Are there known roof, envelope, elevator, mechanical, parkade, plumbing, or exterior projects?
•Are special assessments planned or possible based on current information?
•Is there litigation, a significant insurance deductible, or an insurance concern?
•Are there restrictions that affect pets, rentals, parking, renovations, or your planned use?
•What do recent board and annual meeting minutes reveal?

A condo document review is not an inconvenience. It is an important part of deciding whether a particular building is a good fit.

7. What are your likely next three to five years?

You do not need to predict your entire future before buying a home. But you should consider the next few years. Are you likely to change jobs, expand your family, adopt a pet, need a home office, buy another vehicle, travel extensively, or relocate? Could you stay in the home comfortably if your circumstances changed?

A condo can be a smart first purchase because it may offer an accessible entry point, a convenient location, and lower-maintenance living. A house can be a smart choice if you expect to stay longer, need more space, or place a high value on a yard and private control. The right answer depends on how the property supports your life—not on what someone else says you “should” buy first.

Also consider resale. Look at how the home compares with others in its category. Does it have useful parking? A practical layout? Good natural light? A location that will appeal to future buyers? A manageable condo fee? A well-kept exterior? These features can influence demand when it is time to sell.

But do not buy solely for hypothetical resale. You will be living in the home now. The best choice usually balances your current needs, your budget, and a reasonable view of the future.

A quick comparison: condo, townhome, or detached house

A condominium apartment may fit buyers who want a central location, low exterior-maintenance responsibilities, and a simpler lock-and-leave lifestyle. It may be less suitable for buyers who need a yard, dislike shared walls, or want broad control over pets, rentals, and renovations.

A townhome can offer more space, private entry, and sometimes a small yard or garage. But many townhomes are condominiums, which means condo fees, bylaws, common-property responsibilities, and document review remain important.

A detached house can offer a yard, more privacy, and control over improvements. It also requires you to budget for the full cost of maintenance and repairs. The purchase price may be only one piece of the affordability equation.

A duplex or half-duplex can provide a useful middle option. But its ownership structure matters. Some are condominium properties and some are not. Ask how the property is titled and what shared obligations, fees, or agreements apply.

Make the decision with clear information, not pressure

First-time buyers can feel pressure to decide quickly or choose the “right” property type on the first try. You do not need to do that. You need to understand the numbers, the documents, the location, and the responsibilities before you commit.

Would you rather spend weekends maintaining a yard or enjoying a low-maintenance lifestyle? Is a shorter commute more valuable than extra space? Does the condo fee provide services you will genuinely use? Are you comfortable with the property’s rules and future repair responsibilities?

These are not small questions. They are the questions that help you choose a home that supports your everyday life.

Not sure whether a condo or house is right for you?

Nooran Ostadeian, realtor with RE/MAX Elite Edmonton, offers a complimentary, no-pressure buyer consultation for Edmonton first-time buyers. With more than 18 years of local experience, Nooran can help you compare neighbourhoods, property types, monthly ownership costs, and the practical trade-offs between condos, townhomes, duplexes, and detached homes.

Nooran’s truth-first approach means you will get clear guidance about the benefits and considerations of each option—not pressure to choose a property that does not fit your life. Contact Nooran Ostadeian to start a focused Edmonton home search built around your goals.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca
Read

Edmonton First-Time Home Buyer Programs in 2026: What Is Available After First Place?

If you are saving for your first home in Edmonton, you may be searching for programs that can help you buy sooner. It is a smart question, but it is also an area where outdated online information can create confusion. Program names change, eligibility rules differ, and a program that helped buyers in the past may not be available for a new purchase today.

One program that still appears in many Edmonton homebuyer searches is the City of Edmonton First Place Program. It helped first-time buyers purchase new townhomes in selected developments by deferring the land-cost portion of the mortgage for five years. However, the City of Edmonton now states that, following Council approval on April 15, 2026, there are no remaining sites to be developed under the program and the final sites were developed in 2023.

That is important for buyers: do not build a 2026 buying plan around First Place as a source of new program homes. Instead, use it as a reminder to check every “first-time buyer program” against an official current source. The good news is that eligible Edmonton buyers may still have useful federal savings and tax tools to explore. The right combination can make a meaningful difference in how you save, how you structure your purchase, and how prepared you feel when the right home comes along.

This guide explains what First Place was, why its current status matters, and which first-time home buyer options Edmonton buyers can investigate now.

What was Edmonton’s First Place Program?

First Place was a City of Edmonton program created in 2006 to develop up to 1,000 new townhomes on selected surplus school sites. The goal was to help people and families who had never owned property in Alberta move into homeownership. Homes were sold at market price, but the land-cost portion of the mortgage was deferred for five years, helping buyers manage the initial affordability hurdle.

The program was connected to specific City sites, builders, and developments. It was not a general cash grant that any Edmonton buyer could apply to for any resale home. The City’s description explains that the program worked with banks and builders to develop townhomes on the designated sites and that the five-year deferral applied to the land portion of the mortgage.

This distinction matters because online articles sometimes describe First Place as if it were a permanent citywide down-payment program. It was not. It was a development-specific initiative with a defined number of sites and homes.

As of the City’s April 15, 2026 update, there are no remaining sites to be developed under First Place. The historical information may still be useful if you are researching an existing First Place community or considering the resale of a former program home, but it should not be presented as an available path to a newly built First Place home in Edmonton today.

If you are considering a resale property in a former First Place development, ask your REALTOR and lawyer to confirm the property’s current title, any historical registrations, and whether there are any obligations that affect the particular property. Do not rely on a general online description. The property documents and legal advice are what matter.

What first-time home buyer options can Edmonton buyers explore today?

While First Place is no longer creating new program sites, eligible buyers may have access to federal tools that help them save for, finance, or receive tax relief related to a first home. These are not automatic grants, and they do not replace the need for mortgage qualification. They can, however, become part of a thoughtful Edmonton home buying strategy.

The right question is not, “Which program will buy a home for me?” The better question is, “Which programs am I eligible to use, and how can they work together with my savings, mortgage approval, and purchase timeline?”

1. First Home Savings Account (FHSA)

For many future first-time buyers, the First Home Savings Account is the first program worth learning about. An FHSA is a registered plan designed to help eligible first-time home buyers save for or build a qualifying first home. Contributions are generally tax-deductible, and qualifying withdrawals can be tax-free when the program conditions are met.

The Canada Revenue Agency states that the first year you open an FHSA, the participation room is $8,000. The federal government’s consumer guidance indicates a lifetime contribution limit of up to $40,000. The account is not simply a savings account with a new name. It has eligibility criteria, contribution rules, withdrawal rules, and potential tax consequences if used incorrectly.

For an Edmonton buyer who is several years away from purchasing, an FHSA may provide time to make regular contributions and build a dedicated home savings fund. For a buyer who expects to purchase sooner, it may still be worth discussing with a financial institution or tax professional, because the timing of opening an account and making contributions matters.

Questions to discuss with a qualified advisor include:

•Am I eligible to open an FHSA as a first-time home buyer?
•How much contribution room do I have this year?
•What investment or savings option is appropriate for my purchase timeline?
•What counts as a qualifying withdrawal?
•How will an FHSA fit with my other savings, RRSPs, and mortgage plan?

The CRA FHSA information is the official place to review the program rules before making a decision.

2. The Home Buyers’ Plan (HBP)

The Home Buyers’ Plan allows eligible individuals to withdraw funds from their Registered Retirement Savings Plans (RRSPs) to buy or build a qualifying home for themselves or a specified disabled person. The current HBP withdrawal limit is $60,000, subject to the program rules and eligibility conditions.

For buyers who have money in RRSPs, the HBP can be a useful part of a down-payment plan. But it is not free money. The withdrawal must generally be repaid according to the program rules, and buyers need to understand how using retirement savings affects their long-term financial goals.

The CRA notes that people making their first HBP withdrawal between January 1, 2026, and December 31, 2028 receive temporary repayment relief. For a first withdrawal in 2026, the first repayment year is 2031 rather than 2027. That can ease the early years of homeownership, but it does not eliminate the repayment obligation. A buyer should understand the future payments before relying on the program.

One useful feature is that eligible buyers can use a qualifying FHSA withdrawal and an HBP withdrawal for the same qualifying home, as long as they meet the conditions of each program at the time of withdrawal. For some Edmonton couples, this can be part of a coordinated savings strategy. For others, it may be unnecessary or not appropriate. Mortgage, tax, and investment advice should be personalized.

Read the current details directly through the CRA Home Buyer’s Plan page, then speak with the professionals who understand your personal situation.

3. The federal Home buyers’ amount

Eligible first-time buyers may be able to claim the federal Home buyers’ amount. The Financial Consumer Agency of Canada explains that this can provide a non-refundable tax credit of up to $1,500. It will not fund your down payment or replace closing-cost savings, but it can be a helpful tax benefit after a qualifying purchase.

The important word is “eligible.” Tax credits have definitions and conditions. Do not assume you qualify because you are buying your first property in Edmonton. Review the current Canada Revenue Agency guidance or speak with a tax professional when you prepare your return.

Small benefits still matter in a first year of ownership. New buyers often face moving costs, furniture purchases, utility setup, and small repairs. A tax credit is not a reason to buy a home, but it can be part of a responsible plan.

4. GST/HST new housing rebates and other property-specific options

If you are buying a new home or a substantially renovated home, you may be eligible for a GST/HST new housing rebate in certain circumstances. The federal consumer agency lists this among possible homebuyer programs and incentives. Eligibility is not universal, and the details depend on the type of property, purchase arrangement, and tax rules.

This is especially relevant for buyers considering a new build, a pre-construction condo, or a new townhome. Do not rely on a sales brochure or a general online article alone. Ask the builder, your lawyer, and a tax professional what taxes are included in the price, which rebates may apply, and what paperwork is required.

New construction also brings other questions: builder licensing, warranty coverage, completion dates, upgrades, landscaping, closing adjustments, and any condominium documents. The Government of Alberta advises buyers to research builders, check warranty status, review title and legal considerations, and consider a home inspection. A new home can be an excellent choice, but it still requires careful due diligence.

5. The most important “program” is a prepared purchase plan

Programs can help, but they are not a substitute for a strong personal plan. The buyers who feel most confident are usually the ones who understand their real budget, have a clear savings goal, obtain mortgage guidance early, and choose a home that fits their monthly life.

Your purchase plan should include:

•A down-payment target
•Closing-cost savings
•A deposit amount that is accessible when needed
•A reserve for moving, setup, and unexpected expenses
•A comfortable monthly ownership cost
•A clear picture of the location and property type that fit your lifestyle
•A realistic timeline for mortgage pre-approval, viewing homes, conditions, and possession

The Financial Consumer Agency of Canada recommends planning for closing costs of roughly 1.5% to 4% of the purchase price. That is why a home buying plan should never be based on the down payment alone.

For buyers using an FHSA or HBP, add another step: confirm the program rules before you write an offer. You do not want to discover a missing condition or timing issue after you have committed to a property.

Why accurate local information matters

Home buying content often uses big promises: “Buy with no money down,” “Grant money waiting for you,” or “Don’t miss this city program.” Those statements can attract attention, but they can also mislead buyers.

A better approach is to separate helpful tools from unrealistic expectations. Edmonton buyers should verify whether a program is active, whether they are personally eligible, what the program requires, and how it fits into their full financial picture.

For example, First Place was a real City of Edmonton initiative that helped many buyers in designated developments. It is also no longer creating new sites. Reporting both facts is more useful than promoting an outdated program just because the name gets searched.

That same standard applies to every program. Check official sources, ask your lender or tax professional for personalized advice, and work with a local REALTOR® who will tell you what is relevant now—not only what sounded good years ago.

How Nooran Ostadeian helps Edmonton first-time buyers

The most valuable support in a first purchase is often not a single program. It is having a clear process and an experienced local professional who helps you connect the pieces.

Nooran Ostadeian, REALTOR with RE/MAX Elite Edmonton, can help you clarify your location and property priorities, compare homes and neighbourhoods, understand the local buying process, evaluate a property’s trade-offs, and move through an offer, conditions, and closing with better information. Nooran does not replace the advice of a lender, lawyer, inspector, accountant, or condo-document reviewer. She helps ensure the right questions reach the right professional at the right time.

With more than 18 years of Edmonton real estate experience and a truth-first philosophy, Nooran’s focus is on helping buyers make an informed decision—not pressuring them into a purchase.

Ready to create your Edmonton first-time buyer plan?

Are you saving for a down payment but unsure whether an FHSA, RRSP withdrawal, or tax credit applies to you? Are you wondering which Edmonton neighbourhood and property type fit your budget? Would you like a clear buyer roadmap before you start touring homes?

Contact Nooran Ostadeian at RE/MAX Elite Edmonton for a complimentary, no-pressure first-time buyer consultation. Together, you can map your home search around your actual budget, preferred lifestyle, and next steps—using current, accurate information rather than outdated program promises.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read

The Edmonton First-Time Home Buyer Checklist: From Pre-Approval to Possession Day

Buying your first home is a major life decision, and it can feel as if every step has a new form, deadline, or unfamiliar word. The process becomes much easier when you follow it in the right order. A strong Edmonton first-time home buyer plan starts well before the first showing and continues until you have the keys in your hand.

This checklist is designed to help Edmonton buyers understand what happens from pre-approval to possession day. It does not replace legal, mortgage, tax, or inspection advice. Instead, it gives you a practical road map so you know which questions to ask, which professionals may be involved, and where your attention matters most.

Every purchase is different. A downtown condominium, a south Edmonton townhome, a newer duplex, and an older detached home can come with different considerations. But the basic structure of a thoughtful home purchase remains the same: prepare your finances, understand your needs, view homes carefully, write an informed offer, satisfy your conditions, and prepare for a smooth closing.

1. Define what “the right home” means for your life

Before you look at listings, get clear on why you want to buy. It sounds obvious, but it saves buyers from spending time on homes that do not fit their real priorities.

Start with your daily life. Where do you work? How long are you comfortable commuting? Do you want to be close to family, schools, parks, LRT access, restaurants, or major roads? Do you need a garage, home office, extra bedroom, fenced yard, or low-maintenance lifestyle? Are you planning to stay for two years, five years, or longer?

Then divide your list into three categories: must-haves, strong preferences, and nice-to-haves. A must-have might be a certain number of bedrooms, an accessible layout, or a location near a particular school. A strong preference could be a garage or updated kitchen. A nice-to-have might be a finished basement, walk-in closet, or specific exterior style.

The point is not to lower your standards. It is to make trade-offs intentionally. Edmonton offers a wide range of housing styles and neighbourhoods. Buyers who know their priorities can recognize a good fit faster and make a more confident decision when the right home appears.

2. Review your full financial picture

A mortgage pre-approval is important, but your own budget is the foundation. Look at your income, debts, recurring expenses, savings, and future plans. Think about what payment would let you own a home comfortably while still saving, enjoying your life, and handling surprises.

Your budget should include more than mortgage principal and interest. Plan for property taxes, home insurance, heat, electricity, internet, moving costs, and maintenance. If you are buying a condominium, add the condo fee and understand what it covers. If you are buying a detached home, make space in your budget for future repairs, lawn care, snow removal, and seasonal maintenance.

The Financial Consumer Agency of Canada also reminds buyers to prepare for one-time closing costs, such as legal fees, home inspection costs, property tax adjustments, and title insurance where applicable. It suggests budgeting approximately 1.5% to 4% of the purchase price for upfront costs. Your actual costs can vary, but knowing they exist will help you set a realistic savings target.

Ask yourself three practical questions:

•What monthly payment feels comfortable, even if rates or expenses change?

•How much cash will I have left after closing?

•What financial goals do I want to protect after I buy?

Those answers are more useful than simply searching at the top of your approval range.

3. Speak with a mortgage professional and get pre-approved

Once you understand your personal budget, speak with a bank or mortgage professional. A pre-approval can help you understand your potential borrowing amount, available rates, estimated payments, and the documents a lender may require.

Be prepared to share information about employment, income, debt, savings, and credit. If you are self-employed, recently changed jobs, receive variable income, or are receiving help with the down payment, mention that early. Clear information up front reduces last-minute surprises later.

A pre-approval should guide your search, not dictate it. A lender may approve a maximum amount that is higher than what you want to spend. Your comfort level, lifestyle, and ownership costs should still shape your target range.

It is also a good time to ask about first-time buyer options. Eligible buyers may use an FHSA, the Home Buyers’ Plan, or the federal Home buyers’ amount, subject to their individual eligibility and program conditions. A lender, accountant, or tax professional can help you understand what fits your circumstances.

4. Choose a REALTOR who understands your goals

Your REALTOR should be more than the person who opens a door. A good Edmonton buyer representative helps you organize the search, understand neighbourhoods and property types, compare homes, prepare offers, navigate conditions, and manage the many details between acceptance and possession.

In Alberta, if you decide to work with a real estate agent, you will enter into a written service agreement before the agent begins showing you homes. The Government of Alberta explains that this agreement outlines the exclusive working arrangement and that an agent must disclose potential conflicts of interest. Read the agreement, ask questions, and make sure you understand how the relationship works.

Nooran Ostadeian, REALTOR with RE/MAX Elite Edmonton, takes a truth-first approach to helping buyers. That means being direct about a property’s strengths, trade-offs, location, condition, and possible concerns—not just pointing out attractive finishes. For a first-time buyer, clarity is valuable. You want to feel excited about your home, but you also want to understand what you are choosing.

5. Set up a focused Edmonton home search

Once your budget and priorities are clear, create a search that reflects them. Your search can include location, property type, price range, bedrooms, bathrooms, parking, age, lot size, or condo features.

Stay open enough to learn from the market. You may discover that a townhome gives you better space and location than a detached house in the same price range. You may decide that a smaller condo in a walkable location fits your lifestyle better than a larger home with a longer commute. The search process is not only about finding a listing. It is about refining what matters to you.

As you view homes, keep notes. It is easy to confuse details after several showings. Record what you liked, what concerned you, how the home felt, what repairs you noticed, and how the location worked for your routine. Photos and short notes can help you compare properties with a clearer mind later.

6. View homes with both excitement and discipline

A showing is your opportunity to see beyond the online photos. Pay attention to natural light, layout, storage, sound, parking, traffic, surrounding homes, and the condition of major visible elements. In an older home, look carefully at windows, roof condition, mechanical systems, grading, and signs of moisture. In a newer home, consider construction quality, unfinished work, warranty information, and the surrounding development plan.

Do not expect to diagnose a home yourself. That is not the purpose of a showing. But do notice questions that should be investigated further. A buyer who slows down and asks thoughtful questions is not being difficult. They are protecting a major investment.

For condominium homes, look beyond the unit. Consider the entry, hallways, parkade, elevator, storage, garbage area, common spaces, visitor parking, and exterior condition. Your purchase includes an interest in common property, so the overall building matters.

7. Decide when a home is worth an offer

The perfect home is rare. The goal is to find a home that meets your important needs, fits your budget, and offers a level of condition and location you understand. When you find one, your REALTOR can help you review comparable sales, current competition, days on market, property condition, and the seller’s stated preferences where available.

Remember that asking prices and active listings do not determine a home’s value by themselves. Recent comparable sales and the property’s individual features matter. Nooran’s approach is to look carefully at the evidence, not simply encourage a buyer to offer more to win.

Before you write, ask:

•Does this home meet my must-haves?

•What repairs or updates should I plan for?

•How does the location support my life?

•What would make me comfortable walking away if the terms do not work?

•Can I afford this home after closing, not just on offer day?

8. Write a thoughtful offer with the right conditions

A residential purchase contract sets out the key terms of the sale, including the price, deposit, possession date, included items, financing terms, and conditions. The Government of Alberta notes that a standard residential contract includes details such as the deposit, offered purchase price, and applicable taxes. You may choose to have a lawyer review an agreement before signing.

Conditions are not a weakness. They are a way to investigate important details before a purchase becomes final. Common conditions can include financing, home inspection, review of condominium documents, or other matters relevant to the property.

The right conditions depend on the home and your circumstances. A detached home may call for a strong inspection condition. A condo purchase may require a careful document review. A new home purchase may require questions about builder licensing, warranty, specifications, and completion timing. Your REALTOR can help you understand the options, but decisions about financing, inspection results, legal advice, and contract terms should be made with the appropriate professional guidance.

9. Deliver the deposit exactly as required

Once an offer is accepted, the deposit is due according to the contract. Follow the instructions and deadline carefully. The deposit is normally held in trust and credited toward the purchase on closing, but the contract governs the specific details.

Do not assume that a delay is harmless. If you have questions about how to deliver the deposit, ask immediately. Good communication early in a transaction can prevent avoidable stress later.

10. Complete the financing condition

Pre-approval is only the beginning. Once you have an accepted offer, your lender will review the property and your full file before giving final financing approval. They may request updated documents, an appraisal, explanations of deposits, or additional information.

Respond quickly and accurately. Avoid taking on new debt, changing jobs, making unexplained large transfers, or opening new credit accounts while your financing is being finalized. If something changes, speak with your lender immediately.

Your goal is not merely to remove the financing condition. Your goal is to understand the mortgage you are accepting: the rate, term, payment, amortization, prepayment options, penalties, and renewal considerations. A mortgage is a major long-term commitment. Take the time to ask questions.

11. Arrange a professional home inspection

A home inspection provides an informed opinion about accessible systems and components. Alberta notes that buyers may consider inspecting major systems such as plumbing, electrical, heating and cooling, as well as exterior elements such as roofing and siding. It also notes that licensed home inspectors must meet educational and other requirements.

An inspection does not make a home perfect and it cannot reveal everything behind walls or under the ground. Its value is that it helps you understand the home’s visible condition, prioritize repairs, and make a decision with better information.

Attend the inspection if possible. Ask the inspector to explain the most important findings, which issues are urgent, what requires monitoring, and what maintenance the home will need. If a concern appears significant, you may need further advice from a qualified contractor or specialist.

12. Review condo documents or property-specific information

If you are buying a condominium, document review is a major part of due diligence. You are not only buying the unit. You are joining a condominium corporation and sharing responsibility for common property.

The Government of Alberta explains that condo buyers may review technical documents such as the condominium plan, bylaws, management agreement, phased development disclosure, and home warranty contract. Alberta also requires condominium corporations to maintain specified documents and make them available to owners, purchasers, and mortgagees upon request.

Look for information about the reserve fund, budget, financial statements, insurance, meeting minutes, bylaws, planned work, special assessments, litigation, parking, storage, pets, rentals, and use restrictions. Many buyers choose to hire a qualified condominium document reviewer or seek legal advice. This is not a place to rush.

For a detached home, ask about property-specific documents and information that may affect your decision, such as permits, real property reports, encroachments, renovations, leases, or included equipment. Your lawyer will also be involved in reviewing title and completing the legal transfer.

13. Prepare for closing and possession day

Once conditions are removed, the focus shifts to closing. Your lawyer will handle legal documents, title transfer, mortgage registration, and the flow of funds. Your lender will provide mortgage instructions. Your insurer will arrange the required insurance. Your REALTOR will help coordinate the transaction details and keep the process moving.

Before possession, create a simple checklist:

•Arrange home insurance effective on possession day

•Confirm your down payment and closing funds with your lawyer

•Set up utilities and internet

•Book movers or arrange help

•Plan key pickup and time away from work if needed

•Change your mailing address

•Arrange parking or elevator bookings if moving into a condo

•Prepare a first-week budget for groceries, supplies, locks, cleaning, and small repairs

Possession day can be emotional and busy. A well-organized plan gives you more time to enjoy it.

14. Start homeownership with a maintenance plan

Your purchase does not end when you get the keys. Start a home file with your inspection report, warranties, appliance manuals, condo documents, receipts, utility account details, and contact information for reliable service providers.

Create a simple annual maintenance calendar. Change furnace filters, inspect caulking, clean gutters where applicable, service mechanical systems as needed, watch for water issues, and address small repairs before they become expensive. If you own a condo, stay informed by reading board notices and annual meeting materials.

Homeownership is not about having every answer on day one. It is about staying organized, asking good questions, and making thoughtful decisions over time.

Ready to begin your Edmonton home search?

Have you been pre-approved but are not sure which neighbourhood or home type fits your budget? Are you worried about making a first-time buyer mistake? Do you want honest advice before you feel pressure to make an offer?

Nooran Ostadeian, REALTOR with RE/MAX Elite Edmonton, offers a complimentary, no-pressure first-time buyer consultation. With more than 18 years of local real estate experience, Nooran can help you understand the process, compare Edmonton neighbourhoods, evaluate homes carefully, and move forward at a pace that feels right for you.

Contact Nooran Ostadeian today to request your personalized Edmonton first-time home buyer roadmap.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read

When Should You Reduce Your Listing Price? Does It Always Help?

A price reduction can be an important decision, but it should not be the automatic response whenever a home does not receive an offer.

Sometimes the asking price is too high for the current market. In other cases, buyers are reacting to condition, presentation, difficult showing access, weak photography, or stronger competition nearby.

Reducing the price may help—but only when the new price changes how buyers see the property.

What does a price reduction actually do?

A price reduction can place a home into a different buyer search range, create renewed attention online, and make the property more competitive against similar listings.

However, a small reduction may not change the property’s position. If buyers still see the home as poor value, the same objections may remain.

The purpose of a price adjustment is not simply to show that the seller is willing to negotiate. It is to reposition the property so that it becomes more compelling to the right buyers.

Signs that the price may be too high

The price deserves a careful review when:

• Comparable homes are selling for less
• Similar properties are receiving more showings or offers
• Buyers consistently describe the home as overpriced
• The property has had strong online views but few showings
• The home has received showings but no serious interest
• New competing listings offer more features at a similar price
• The property has been listed long enough that the initial launch advantage has passed

No single sign proves that the price is wrong. The pattern matters.

Active listings are not proof of value

Sellers often compare their home with other properties currently listed for sale. Those asking prices can provide context, but they do not prove what buyers are willing to pay.

A property can be listed at any price. A completed sale gives stronger evidence because it shows what a buyer actually agreed to pay under real market conditions.

A good pricing review considers recent sold properties first, then uses active listings to understand the competition.

Nooran Ostadeian helps Edmonton sellers review recent sales, current competition, and buyer response so price decisions are based on evidence—not guesswork.

When reducing the price may help

A price adjustment may be appropriate when the home is well presented, easy to show, accurately marketed, and still receiving little serious interest compared with similar properties.

It may also help when the original price was based on outdated market conditions, an overly optimistic valuation, or a comparison with a substantially superior property.

The new price should be meaningful enough to improve the property’s position. The exact adjustment depends on the price range, competition, recent sales, and the seller’s objectives.

When reducing the price may not solve the problem

A lower price may not fix the situation when:

• The home is difficult to access for showings
• The photos do not show the property well
• The home has strong odours or visible clutter
• Basic repairs have been ignored
• The description does not communicate the property’s strengths
• The listing is competing against recently renovated homes
• The property has restrictions or features that buyers do not understand
• The seller is receiving very little showing activity because of limited availability

In these cases, reducing the price without addressing the underlying issue may simply mean selling for less without improving the buyer response.

Should the price reduction be small or substantial?

There is no universal percentage that works for every listing. A reduction should be based on market evidence and the buyer pool the seller wants to reach.

A small reduction may be appropriate when the property is only slightly outside the expected range. A larger adjustment may be necessary when the price has placed the home in the wrong competitive category.

The decision should consider the likely financial effect, the seller’s timing, the cost of remaining on the market, and the risk of chasing the market with several small reductions.

Ask these questions before changing the price

Before reducing the asking price, review:

1. What similar homes have actually sold recently?
2. What are buyers choosing instead?
3. How does this property compare in condition, layout, location, and features?
4. How many qualified buyers have viewed the home?
5. What objections have been repeated?
6. Is the property easy to access and present well?
7. Will the proposed price reach a meaningfully different group of buyers?
8. Is there a better marketing or preparation change that should happen first?

A price reduction is not a failure

Adjusting a price is not necessarily an admission that the home was listed badly. Markets change, new information becomes available, and buyer behaviour can be different from what was expected.

A well-reasoned adjustment can protect the seller’s time and equity by responding to the market rather than ignoring it.

The important thing is to avoid making an emotional change based on one comment or one quiet week. Look for patterns and make the decision with complete information.

The Truth-First takeaway

A price reduction does not automatically create a buyer. The right price, accurate marketing, good presentation, reasonable showing access, and honest positioning all work together.

The goal is not to choose the lowest price. The goal is to position the home so the right buyers recognize its value and feel confident taking the next step.

If you are considering a price adjustment for your Edmonton listing, Nooran Ostadeian can help you review recent sales, current competition, buyer feedback, presentation, and the most practical path forward.

Before changing the price, review the other common reasons a home may not be selling in Why Isn’t My Edmonton Home Selling? 10 Common Reasons Buyers Are Passing.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read

Why Isn’t My Edmonton Home Selling? 10 Common Reasons Buyers Are Passing

If you’re wondering why your Edmonton home isn’t selling, the answer is not always as simple as reducing the price.

Listing your home can be frustrating, especially when you believe the property is attractive, well located, and fairly priced. When showings are happening but offers are not, it is natural to wonder what buyers are seeing that you are not.

Sometimes the problem is price. Sometimes it is presentation, condition, access, marketing, or the competition. Often, several smaller issues combine to make buyers hesitate.

Here are ten common reasons an Edmonton home may not be selling as expected.

1. The asking price is ahead of the market

The most common reason a home does not sell is that buyers do not believe the property offers enough value at the current price.

This does not necessarily mean the home is not worth what the seller hopes to receive. It means buyers are comparing it with recently sold homes and competing properties available today.

A pricing review should focus on comparable sales, current competition, condition, location, and buyer activity—not only on the seller’s original purchase price or the amount invested in renovations.

2. The home is being compared with the wrong properties

A nearby property is not always a true comparable. A home may differ in lot size, floor plan, basement development, garage, renovation quality, location, or exposure to traffic and noise.

Comparing a property with the wrong homes can lead to an asking price that appears reasonable on paper but does not match how buyers actually see the market.

3. The first impression is not strong enough

Buyers often form an opinion within the first few moments of seeing a property online or entering the home.

A cluttered entrance, overgrown yard, poor lighting, strong odours, damaged flooring, or tired paint can make buyers focus on work and expense instead of the home’s strengths.

The goal is not to make every home look perfect. The goal is to remove avoidable distractions so buyers can understand the property properly.

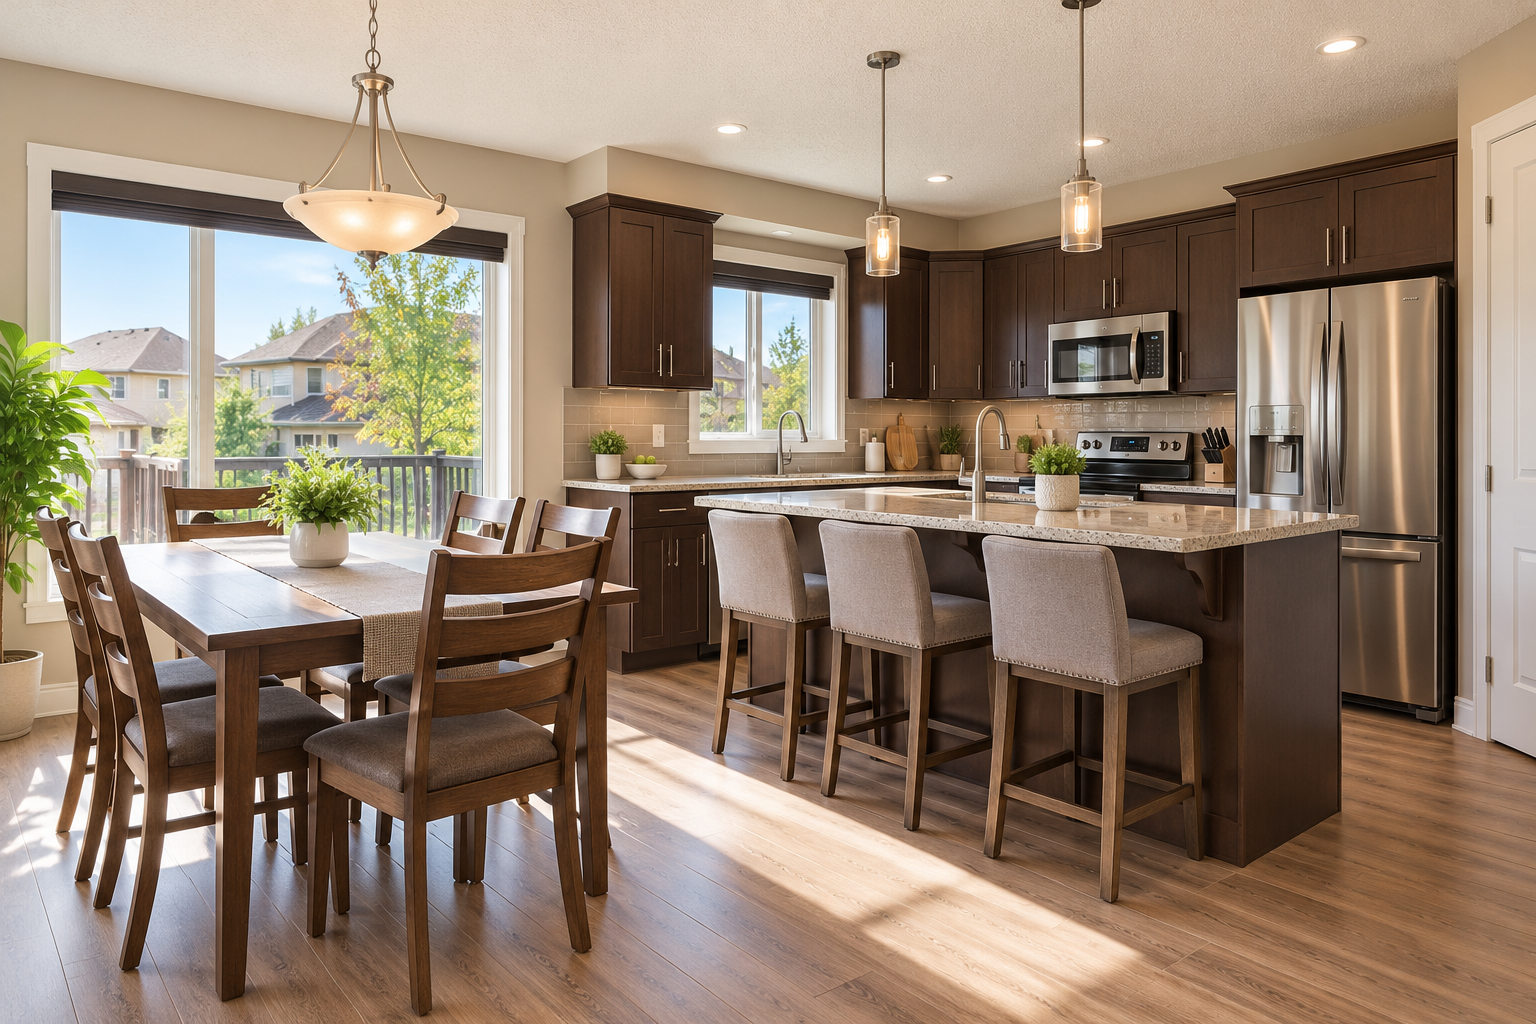
Clean kitchen and dining area prepared for an Edmonton home showing

4. The photos do not represent the home well

For many buyers, the first showing happens online. Dark, inconsistent, poorly framed, or outdated photos can reduce interest before a buyer ever books an appointment.

Good photography should show the layout honestly, include the most important features, and help buyers understand how the rooms connect. It should not make the home look larger or more luxurious than it really is.

5. The home is difficult to show

A property may be well priced, but if it is difficult to view, buyers may move on to another option.

Limited showing hours, short notice, pets that are not secured, rooms that cannot be accessed, or repeated cancellations can reduce the number of serious buyers who see the home.

Showing instructions should be reasonable, clear, and coordinated with everyone living in the property.

6. The home is not being maintained during the listing

A home can be clean and presentable at the time of listing but become less appealing if daily maintenance is overlooked.

Garbage, dirty bathrooms, unmade beds, full countertops, strong food or pet odours, and unkept outdoor areas can affect a buyer’s impression. This is especially important when the property is tenant-occupied.

The seller and tenant should discuss expectations before the home is listed. The conversation should be respectful, practical, and consistent with the tenancy agreement and applicable Alberta requirements.

7. The marketing does not explain the real value

A listing description should do more than repeat the number of bedrooms and bathrooms. It should explain what makes the property useful or different.

Is the home close to a school, transit, shopping, trails, or employment areas? Does it have an unusual lot, a functional layout, recent mechanical upgrades, a legal suite, a heated garage, or strong redevelopment potential?

Buyers need clear information to understand why the property deserves their attention.

Nooran Ostadeian works with Edmonton sellers to identify the features buyers are most likely to value and position each property around its real strengths—not just its basic specifications.

8. The property has unresolved maintenance concerns

Small repairs may not seem important to the seller, but buyers often notice them quickly. Peeling paint, loose railings, damaged trim, dripping taps, cracked caulking, or signs of moisture can make buyers wonder what larger problems may exist.

Not every repair needs to be completed before selling. However, sellers should understand which concerns are likely to affect buyer confidence and address the most visible or important issues first.

9. The home is competing with a stronger option

A property may be attractive on its own but less attractive beside the other homes currently available in the same price range.

Buyers may be comparing renovations, lot size, garage space, basement development, monthly costs, location, and move-in readiness. The question is not only, “Is this home good?” It is also, “Why would a buyer choose this home over the alternatives?”

10. The market has changed since the listing began

Market conditions can shift while a home is listed. New competition may appear, buyers may become more cautious, or the property may lose the advantage it had when it first came on the market.

That is why a listing should be reviewed regularly rather than left unchanged for weeks. A useful review looks at showing activity, online engagement, buyer comments, new competition, recent sales, and the overall position of the property.

What should a seller do next?

Do not automatically reduce the price before understanding the actual problem. First, review:

• How many serious showings have occurred
• What buyers and agents are saying
• How the listing compares with current competition
• Whether the photos and description are strong
• Whether the home is easy to show
• Whether the condition matches the asking price
• What comparable properties have recently sold for

The answer may be a price adjustment, but it could also be better preparation, improved access, updated marketing, or a combination of changes.

The Truth-First takeaway

A home that is not selling is giving you information. The important question is not how to defend the current price. It is how to understand what the market is communicating and make the right adjustment.

If your Edmonton home has been listed longer than expected, Nooran Ostadeian can provide a straightforward review of the pricing, presentation, competition, and showing experience so you can make a decision based on evidence—not pressure.

If you are wondering whether the problem is your asking price, read When Should You Reduce Your Edmonton Listing Price? Does It Always Help?

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca
Read

Edmonton Property Assessment vs. Market Value Before Selling

If you are preparing to sell an Edmonton home, the assessed value on your City notice is worth understanding—but it should not be treated as an automatic asking price. An assessment is a City-produced, date-specific estimate used for the property-tax system. A current sale-price discussion needs to consider the home itself, recent comparable sales, active competition, and today’s market conditions.

Understanding the difference can make the selling process much clearer.

What an Edmonton Property Assessment Is For

In Alberta, property assessments are used to help distribute municipal and education property taxes among property owners. Edmonton property assessments are prepared annually and are based on a mass-appraisal process.

For residential property, the assessed value is the City’s estimate of what the property would have sold for in the open market on a specific past date. It is a standardized estimate created for the assessment system. It is not a prediction of what a buyer will offer for your home today.

Your assessment is still useful. It can help you review the City’s property record and understand how the City has described the home. However, it is not a listing strategy, a buyer’s offer, or a substitute for current market evidence.

Why the Assessment and Sale Price Can Be Different

The biggest reason is timing. The 2026 Edmonton assessment cycle is based on a July 1, 2025 market-value date, using information available at that time and physical changes recorded through December 31, 2025. A home being listed in September 2026 is entering a market more than a year after that assessment value date.

Markets can change during that period. Inventory, buyer demand, interest rates, property condition, neighbourhood activity, and competing listings can all affect how a specific home is positioned when it goes on the market.

A second reason is that every home is different. Buyers compare location, lot size, layout, condition, updates, parking, outdoor space, age, style, and nearby alternatives. A City assessment cannot fully capture how buyers will respond to your particular home in the current market.

A third reason is the accuracy of the City’s property record. If a record is missing information or includes details that are no longer correct, the assessment may not fully reflect the home as it existed on the assessment date. On the other hand, improvements completed after the assessment condition date may matter to today’s buyers even though they were not part of the prior assessment.

What Homeowners Should Review Before Selling

Start by reviewing your assessment notice and the property information available through the City’s MyProperty portal. Check the basics carefully: property type, finished space, garage information, additions, and the completion status of any renovations or construction.

Keep a simple list of updates you have completed, along with approximate dates. Major improvements such as kitchens, bathrooms, windows, roofing, furnaces, flooring, landscaping, decks, garages, and basement development can help explain the home’s current condition and appeal.

If you believe the assessment record contains an error, contact the City assessor promptly. It is best to deal with an assessment concern as its own issue rather than assuming it will determine the property’s sale price.

What a Comparative Market Analysis Does Differently

A comparative market analysis, often called a CMA, is used to estimate a home’s likely market position by reviewing similar properties that have recently sold in the immediate area. It helps sellers understand how their home compares with current market evidence.

A useful CMA looks at recent sales that are genuinely comparable. This normally means reviewing homes with similar location, style, size, age, condition, features, and lot characteristics. Active listings are also important because they show the alternatives buyers will see at the same time.

A CMA is different from both a City assessment and a formal appraisal. It is a practical tool for planning a listing strategy, setting expectations, and preparing a home for market. It should be updated if meaningful new sales, listings, or changes in the market occur before launch.

A Simple Pre-Listing Plan

Begin by locating your current assessment notice and noting the assessment year and valuation date. Then review the City’s property record and make sure the basic information is accurate.

Next, prepare a list of the home’s updates and features. Include the approximate completion date of major work, details that may not be obvious in photos, and anything a buyer should know about maintenance or improvements.

Then request a current comparative market analysis. Ask which recent sales were selected, why they are comparable, and what active listings buyers will be comparing with your home. This is where the conversation moves from a historical assessment number to a current, property-specific marketing plan.

Finally, revisit the analysis before your home goes live. If new listings appear, similar homes sell, or market conditions shift, your positioning may need to be adjusted.

Understand Your Edmonton Home’s Market Value Before You Sell

Before selling your home in Edmonton, review your property assessment alongside recent neighbourhood sales, competing listings and your home’s condition and improvements. A current comparative market analysis helps connect those details to a realistic asking price and a focused marketing strategy.

Thinking about selling your Edmonton home? Book a complimentary home-value consultation with me, Nooran Ostadeian, REALTOR® with RE/MAX Elite. I’ll help you assess your home’s market position, identify preparation priorities and build a pricing and marketing plan tailored to your property.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read

Best Edmonton Neighbourhoods for First-Time Home Buyers

A first home is not simply a property type or a price point. It is the place that needs to work for your normal weekdays: getting to work or school, picking up groceries, spending time outdoors, hosting friends, and managing the care a home requires. That is why the strongest first-time-buyer search starts with fit, then narrows to homes that meet it.

Edmonton has many communities with different housing styles, amenities, and transit options. Rather than looking for one universally “best” neighbourhood, it is more useful to choose a few areas that suit your lifestyle and then compare the homes, buildings, and blocks within them. Prices, availability, condo fees, and property condition can change quickly, so local comparable sales should always be part of the final decision.

Hairsine: A Practical Choice for Row Homes and Low-Rise Apartments

Hairsine is a northeast Edmonton community worth exploring if you are open to row housing, townhomes, or low-rise apartments. These housing types can offer a different balance of space, maintenance, and ownership costs than a detached house.

For first-time buyers, Hairsine can be a useful area to compare attached-home options. Some buyers may appreciate the neighbourhood’s established feel, nearby green space, and the opportunity to look at several home styles rather than focusing only on single-family homes.

Before making a decision, look closely at the ownership structure of the property. A condominium townhouse and a freehold-style home can have very different monthly costs and responsibilities. Ask about parking, storage, exterior maintenance, utilities included in any condo fee, insurance, reserve-fund planning, and any upcoming building work.

Transit should also be tested in real life. Plan a door-to-door trip from the exact property to your work, school, or regular destination. Include the walk to the stop, transfer time, evening return trip, and what the route may feel like during winter.

Mill Woods Town Centre: For Buyers Focused on Apartment Living

Mill Woods Town Centre is a strong area to consider if apartment living is your priority. The community has an apartment-focused housing pattern and a central setting around a water feature and park space.

For a first-time buyer, an apartment can provide a lower-maintenance way to enter the market. It can also simplify the home search because you can compare building features, unit layouts, parking, storage, amenities, and monthly fees more directly.

When viewing apartment properties, focus on more than the unit itself. Ask about the condition of common areas, elevators, roofs, windows, heating systems, and parkades. Review the condo documents carefully, including the reserve-fund study, board meeting minutes, insurance information, planned repairs, pet rules, rental rules, and special assessments.

The location may work well for buyers who value nearby services and transit access, but do not assume that a building’s location on a map will automatically make the commute easy. Walk the route, test the timing, and visit at the times of day you would actually be travelling.

Laurel: A Newer Southeast Edmonton Community

Laurel is a southeast Edmonton community that can appeal to first-time buyers looking for a newer neighbourhood feel. The area includes a mix of housing forms and is designed with parks, open spaces, and pedestrian connections in mind.

This can be a good place to compare different options, including detached homes, attached homes, and apartment-style properties. Buyers who value newer development, local parks, and access to southeast amenities may find Laurel worth adding to their shortlist.

The broader Meadows area also offers a major community recreation centre with aquatic, fitness, arena, and outdoor facilities. For many buyers, nearby recreation, green space, and everyday services can matter just as much as the number of bedrooms in a home.

Before buying in a newer community, confirm whether the property belongs to a homeowners’ association, condominium corporation, or another ongoing arrangement. Ask what the fee covers, how often it is paid, and what obligations come with ownership. It is also wise to review landscaping, drainage, fencing, decks, grading, and any recently completed work.

King Edward Park: Mature Streets and Ravine Access

King Edward Park is an established southeast Edmonton neighbourhood with a mature, grid-street character. It can be a good fit for buyers who prefer older homes, tree-lined streets, walkability, and access to outdoor space.

The area is close to Mill Creek Ravine, which gives residents access to paved shared-use pathways for walking and cycling. For buyers who want an urban location with nearby nature, that can be a meaningful lifestyle feature.

Mature neighbourhoods often require a more condition-focused search. Two homes on the same street can be very different in terms of renovations, maintenance, drainage, foundation condition, electrical systems, plumbing, roofing, and permits for past work. A professional home inspection and thoughtful questions about major updates are especially valuable.

It is also important to visit more than once. Pay attention to the exact block, street parking, traffic, noise, lighting, access to services, and the route to work or school. A neighbourhood may be a great fit while a particular property or location within it may not be.

How to Compare Edmonton Neighbourhoods

Before choosing an Edmonton neighbourhood, create a simple scorecard for every home you visit. For first-time home buyers in Edmonton, this helps organize your priorities and compare properties. Start with your non-negotiables: home type, bedrooms, parking, monthly budget, commute, public transit, outdoor space, accessibility and future plans. Add notes after each viewing while the details are fresh.

When comparing Edmonton condos, townhouses and detached homes, consider the full cost of ownership. Review mortgage payments, property taxes, condo fees where applicable, insurance, utilities and maintenance responsibilities. Evaluate the property’s condition, ownership structure and specific location alongside its asking price and finished square footage.

Whether you’re exploring homes for sale in Hairsine, Mill Woods Town Centre, Laurel or King Edward Park, focus on how each property fits your daily life. The best Edmonton neighbourhood for your first home will depend on your budget, housing needs, commute and long-term plans.

Ready to buy your first home in Edmonton? Book a complimentary Edmonton real estate consultation with me, Nooran Ostadeian, REALTOR. I’ll help you compare Edmonton neighbourhoods, review current homes for sale and narrow your search around what matters to you.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read

Edmonton Housing Market Update: August 2026

The latest completed Greater Edmonton Area housing-market report is for August 2026. The numbers show a quieter late-summer market, with sales and new listings both lower than July while the number of available residential properties remained higher than the same time last year.

The most useful way to read this update is as a local market snapshot—not as a prediction of what every Edmonton home will do next. Conditions can vary significantly by neighbourhood, property type, price range, condition, and the number of comparable homes currently available.

August 2026 Greater Edmonton Area Market at a Glance

In August 2026, the Greater Edmonton Area recorded 2,143 residential sales. That was down 15.4% from July and down 9.8% compared with August 2025.

There were 3,769 new residential listings during the month. That was down 8.1% from July but 3.3% higher than the same month last year. At the end of August, there were 8,052 residential properties in inventory. This was 15.1% higher than August 2025, giving buyers more properties to compare than they had one year earlier.

The all-residential average selling price was $469,602, while the median selling price was $439,000. The MLS® Home Price Index composite benchmark price was $426,900.

The average time on market for residential properties was 41 days. The sales-to-new-listings ratio was 57%.

What the Numbers Mean

The August results show that the market was less active than it was in July. Sales declined, new listings declined, and average days on market increased slightly. At the same time, inventory was higher than one year earlier.

For buyers, higher inventory can mean more choice. It can make it easier to compare similar homes, take a closer look at condition and value, and consider the full range of available properties. However, it does not mean that every home will have the same level of competition. A well-priced home in a desirable location can still attract strong interest.

For sellers, the higher level of inventory makes property-specific preparation even more important. Buyers can compare your home with the other homes available in the same price range and area. A strong launch includes accurate pricing, professional presentation, clear information about updates and features, and a realistic understanding of the competition.

Detached Homes

Detached homes had the highest sales activity in August, with 1,302 sales. The average selling price for detached homes was $575,575, and the average time on market was 38 days. Detached homes remain an important part of the Greater Edmonton market, but the experience can differ significantly between communities. A newer family home in a growing suburb may attract a different buyer than a mature bungalow in an established neighbourhood or a luxury home in a higher price range.

Semi-Detached Homes

Semi-detached homes recorded 251 sales in August. The average selling price was $424,322, and the average time on market was 41 days.

For many buyers, semi-detached homes can offer a balance between a detached-home feel and a more accessible price point. Buyers will often compare layout, garage space, yard size, location, and the age and condition of the home closely.

Row Homes and Townhomes

Row homes and townhomes recorded 282 sales in August, with an average selling price of $298,238. The average time on market was 45 days.

This category can be attractive for buyers who want more space than an apartment but may prefer a lower-maintenance lifestyle than a detached home. The details matter: condo fees, parking, outdoor space, pet rules, reserve-fund planning, and exterior maintenance responsibilities should all be reviewed carefully.

Apartment Condominiums

Apartment condominiums recorded 308 sales in August. The average selling price was $215,422, and the average time on market was 48 days. Apartment condos can be an accessible entry point into Edmonton homeownership.

Buyers should look beyond the unit itself and review the building’s financial health, reserve fund, insurance, maintenance history, condo fees, parking, storage, and rules around pets or rentals.

Why Local Details Matter

The Greater Edmonton Area numbers are useful for understanding the overall market, but they are not a price estimate for a specific home. An average price, median price, and benchmark price are three different measurements. None of them can replace a focused review of comparable sales in your exact neighbourhood and property type.

A detached home in southwest Edmonton, an apartment condominium near downtown, and a townhouse in a newer southeast community may all be affected by different levels of buyer demand and competing inventory.

Before buying, look at homes that are genuinely comparable in location, style, size, condition, and ownership structure. Before selling, review recent sales and active listings that buyers are likely to compare with your home.

What This Means for Edmonton Buyers and Sellers

August 2026 brought lower sales and fewer new listings than July, while inventory remained higher than a year earlier. The results also varied across detached homes, semi-detached homes, townhomes, and apartment condominiums.

For buyers and sellers, the most useful next step is to connect those broader Edmonton market numbers to the specific home and neighbourhood you care about. Recent comparable sales, active competition, property condition, location, and pricing strategy often matter more than one city-wide headline.

Nooran Ostadeian, Edmonton REALTOR®, helps buyers and sellers understand what the current market means for their specific situation, from reviewing comparable sales and neighbourhood trends to building a realistic buying or selling strategy.

Want to know what the Edmonton real estate market means for your home or your next purchase? Book a complimentary consultation with Nooran today.

Contact Nooran Ostadeian
TOP REALTOR® | RE/MAX Elite
Call at 780-953-0723
Website: realtyedmonton.ca

Read
Categories:   Alberta Home Inspection | alberta oil prices | Alberta Real Estate | Ambleside Edmonton Real Estate | Beautiful city | best nature spots near Edmonton | Best neighborhoods in Edmonton | best restaurants in Edmonton | Best Things About Edmonton | Best walking trails in Edmonton | Buying a Home in Edmonton | buying home in edmonton | CAF Relocation | Canada | CFB Edmonton Relocation | Choosing a neighborhood Edmonton | City Living | Client Loyalty in Real Estate | Cold Winter Edmonton | Condos for Sale in Ambleside | Devon, Devon Real Estate | Downtown Edmonton | Edgemont Edmonton Real Estate | Edmonton Alberta Canada | Edmonton Basements | Edmonton birdwatching locations | Edmonton Communites | Edmonton Condos | Edmonton cultural festivals | Edmonton fall home maintenance | edmonton fall real estate | Edmonton food scene | Edmonton foodie guide | Edmonton Home Buyers | Edmonton Home Buying Guide | edmonton home for sale | Edmonton Home Inspection | Edmonton Home Prices | Edmonton home sales report | Edmonton Home Sellers | edmonton home value | edmonton homes for sale | Edmonton homes for sale July 2025 | edmonton housing market | Edmonton housing market July 2025 | Edmonton Housing market Summer 2026 | Edmonton Housing Trends July 2025 | Edmonton Iranian Community | Edmonton Luxury Homes | Edmonton Market Update | Edmonton migratory birds | Edmonton Military Relocation | Edmonton Neighborhoods | Edmonton Neighbourhoods | Edmonton property prices July 2025 | Edmonton real estate | Edmonton Real Estate Agent | Edmonton Real Estate Market | Edmonton Real Estate Market Update | Edmonton real estate news | Edmonton Real Estate Tips | edmonton realtor | Edmonton summer events 2025 | Edmonton walking trails | Edmonton weekend escape | Edmonton Weekly Market Report | Edmonton winter home preparation | Edmonton Zoning | Fall checklist for Edmonton homeowners | Family-friendly Communities Edmonton | Family-friendly neighborhoods Edmonton | Fast Home Sale Tips | Featured Listings | Festivals | First-Time Home Buyers | Fort Saskatchewan, Fort Saskatchewan Real Estate | Free events Edmonton summer | Freeze-thaw season tips Edmonton | Frozen Pipes | Greater Edmonton Area | GST Rebate | hairsine | Helping programs | Henderson Estates Edmonton | Heritage Festival Edmonton 2025 | Home | Home Buying Tips | home selling tips | Homes for Sale | Homes for Sale in Edmonton | Homes Near CFB Edmonton | House Hunting Trip (HHT) | kingedwardpark | Late summer activities Edmonton | laurel | Leduc, Leduc Real Estate | Listing Strategy Edmonton | Living in Terwillegar Towne | local restaurants Edmonton | Market Update | Market Updates | mill woods | Morinville Real Estate | moving to edmonton | Nature walks Edmonton | nooran ostadeian | Old Riverbend Edmonton | one-day getaways from Edmonton | Pelicans in Edmonton | Plant-based Meals The Keg | Plant-based Steakhouse Options | popular Edmonton dining spots | property types | quick road trips from Edmonton | Radon Gas Edmonton | Radon Testing Edmonton | real estate investment | Real Estate Monthly Update | Real Estate News Edmonton | Realtor in Edmonton | Reasons To Live In Edmonton | relocation to alberta | Repeat Real Estate Clients | Restrictive Covenants | River Valley sunset walks | River valley trails Edmonton | riverdale | Rosenthal Real Estate | Scenic views | Selling a home in Edmonton | Selling Your Home: Expert Tips for Success | SIRVA Canada | Smart Home Tips & Renovation Ideas | South Terwillegar housing market | South Terwillegar Pond pelicans | Southwest Edmonton Homes | Southwest Edmonton Real Estate | St. Albert Real Estate | Strategic Home Pricing | Summer trails Edmonton | Taste of Edmonton | Terwillegar Drive Expansion | Terwillegar Edmonton listings | Terwillegar July 2025 market update | Terwillegar nature spots | Terwillegar real estate market July 2025 | Terwillegar Towne Edmonton | Terwillegar Towne homes for sale | The Uplands Edmonton | Things to do in Edmonton August | things to do near Edmonton | Travel | urban wildlife Edmonton | Vegan Dining | Vegan Options at The Keg | Vegan Special Dining | Vegan-friendly Restaurants | West Edmonton | West Edmonton Real Estate | Westmount Edmonton | where to eat in Edmonton | Where to live in Edmonton | Windermere Edmonton Real Estate | winter activities this november | Winter Home Maintence | winter markets Edmonton | Winterize your home Edmonton | Zone 05, Edmonton Real Estate | Zone 07, Edmonton Real Estate | Zone 12, Edmonton Real Estate | Zone 13, Edmonton Real Estate | Zone 14, Edmonton Real Estate | Zone 15, Edmonton Real Estate | Zone 18, Edmonton Real Estate | Zone 20, Edmonton Real Estate | Zone 21, Edmonton Real Estate | Zone 29, Edmonton Real Estate | Zone 35, Edmonton Real Estate | Zone 53, Edmonton Real Estate | Zone 56, Edmonton Real Estate | Zone 57, Edmonton Real Estate | Zone 58, Edmonton Real Estate
Data last updated on November 11, 2026 at 03:30 PM (UTC).
Copyright 2026 by the REALTORS® Association of Edmonton. All Rights Reserved.
Data is deemed reliable but is not guaranteed accurate by the REALTORS® Association of Edmonton.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services provided by real estate professionals who are members of CREA.